Same pension. Smaller bill.
With salary sacrifice, part of your employee’s pay goes straight into their pension, before it reaches their pay packet.
This saves you money. The government takes a slice of everyone’s pay, in National Insurance. When part of the pay goes into the pension first, there’s less pay for the government to take a slice of. The pension still gets the same amount, and you keep the difference.
For example: if £100 of an employee’s pay goes into their pension this way, you save about £15. Across a whole team, that adds up to thousands of pounds a year.
Your business will save
£0a year on employer National Insurance
This saving is based on switching your scheme, with no change to either your employees or your employer pension contribution.
- Current employer NI bill
- £0
- Employer NI bill with salary sacrifice
- £0
Salary sacrifice savings calculator
See how it works
A short video walks through what salary sacrifice means for your business and your employees.
When switching to us, you can enrol all employees into salary sacrifice as default.
We'll show you exactly how to set up your salary sacrifice scheme, with zero admin headache.
-
Week 1
Agree the plan
We agree your pay dates and how salary sacrifice fits your payroll.
-
Week 2
Set up salary sacrifice
We set up your scheme, with the same contribution percentages your team pays today.
-
Week 3
Tell your team
We help you explain the switch: same contributions, lower NI, and they can still contribute more if they want.
-
Week 4
Go live
Salary sacrifice starts from the next pay run, and your NI saving begins.
Salary sacrifice support
Questions come up during the switch and after it. You get a person to ask, not a webpage.
Free set-up help
We help you set up salary sacrifice at no charge, and check it with your payroll before it goes live.
A named contact for your business
One person who knows your scheme and your pay dates.
Help for your team
Questions about how salary sacrifice affects their pay and pension, answered by a person.
Support is guidance to help your business and your team decide. It is not regulated financial advice.
What we would do for you
Switch to Provider X ahead of your next payroll run.
Pension admin, handled for you
Most pension admin is repeated work. Contribution files go out every pay run. Starters and leavers need updating. The same questions come back again and again.
Moving that work to Provider X frees up your payroll and HR team for the things only you can do.
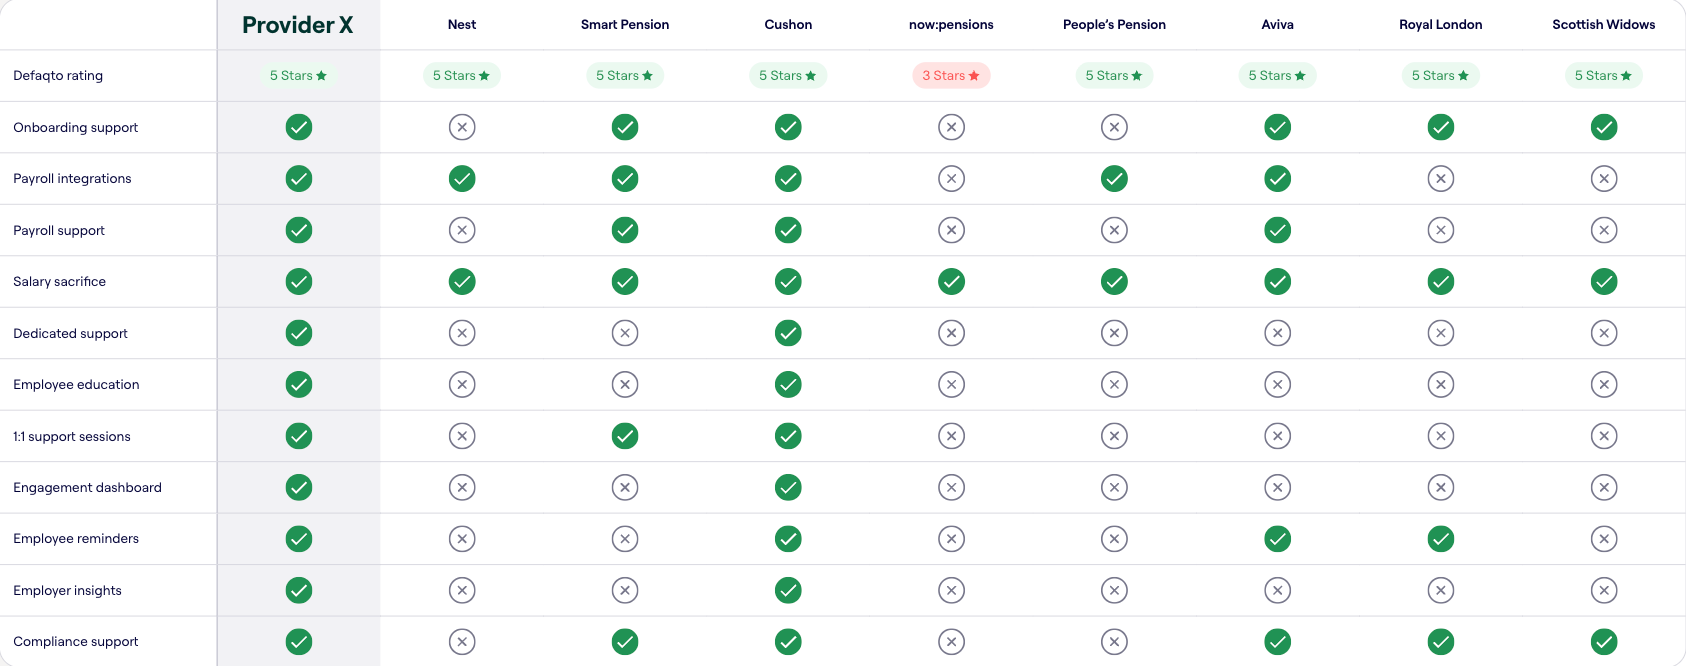
What you get from switching to Provider X
Save time on every pay run
Contributions go across without a manual file to prepare and check each month.
Smarter uploads, fewer headaches
Data checks catch problems before they reach the scheme, not weeks afterwards.
Connect payroll quickly
A payroll link that is set up once, so contributions follow each pay period.
Spot errors early, fix them quickly
Problems are flagged while they are small, with a clear route to put them right.
Easy to set up. Quick to switch.
Switching sounds like a big job. Mostly it is a few conversations. Provider X does the heavy lifting, from setting up your scheme to moving your existing workplace pension across.
- Week 1
A couple of calls
We learn how your business and payroll work, and agree the plan together.
- Week 2
We set up your scheme
We do the heavy lifting, including your salary sacrifice set-up.
- Week 3
Your team hears about it
We help you explain the change and the benefits. Joining is each person’s choice.
- Week 4
Payroll connects
Your payroll links up, so contribution files are handled automatically.
- Week 5
You are live
We move your existing workplace pension across and the first contributions go in.
Support that takes the work off you
Set-up, questions and changes are handled by people who know your scheme.
- Set-up from day oneWe handle the detail of getting your scheme running.
- Your own account managerOne named contact for your business.
- Free for employersNo charge to employers for the service described here.
We take financial wellbeing seriously
Our sessions are designed to educate your employees on how to use their pension to their advantage.
From salary sacrifice to compound interest, we'll help break down all of the pension jargon.
Other providers vs Provider X
This is the common experience across the market, not any one firm.
| Topic | Other providers | Provider X |
|---|---|---|
| Pay run uploads | Manual files, checked by hand | Automatic, with checks before submission |
| Starters and leavers | Updated by hand, often late | Picked up from payroll each pay run |
| Support for employers | Webforms and waiting times | Named account manager and hourly service level |
| Set-up | Long, with many steps for you | Done with you in a few weeks |
Your team actually uses it
A pension is only useful if people look at it. Provider X is built to get them looking.
Added features for your employees
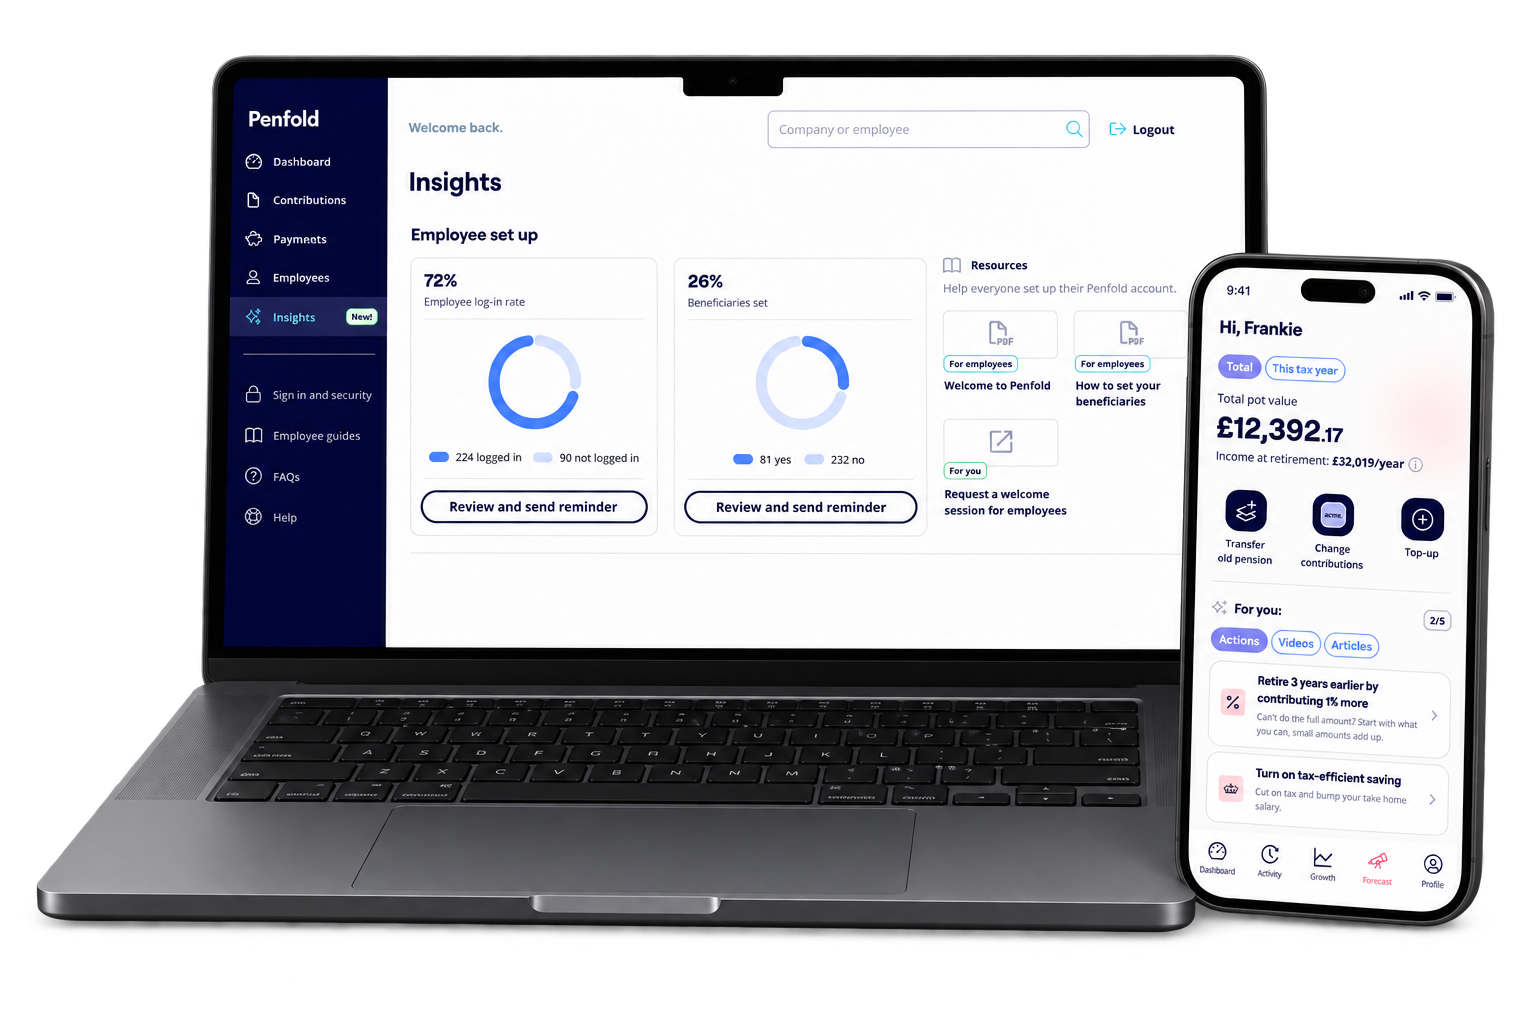
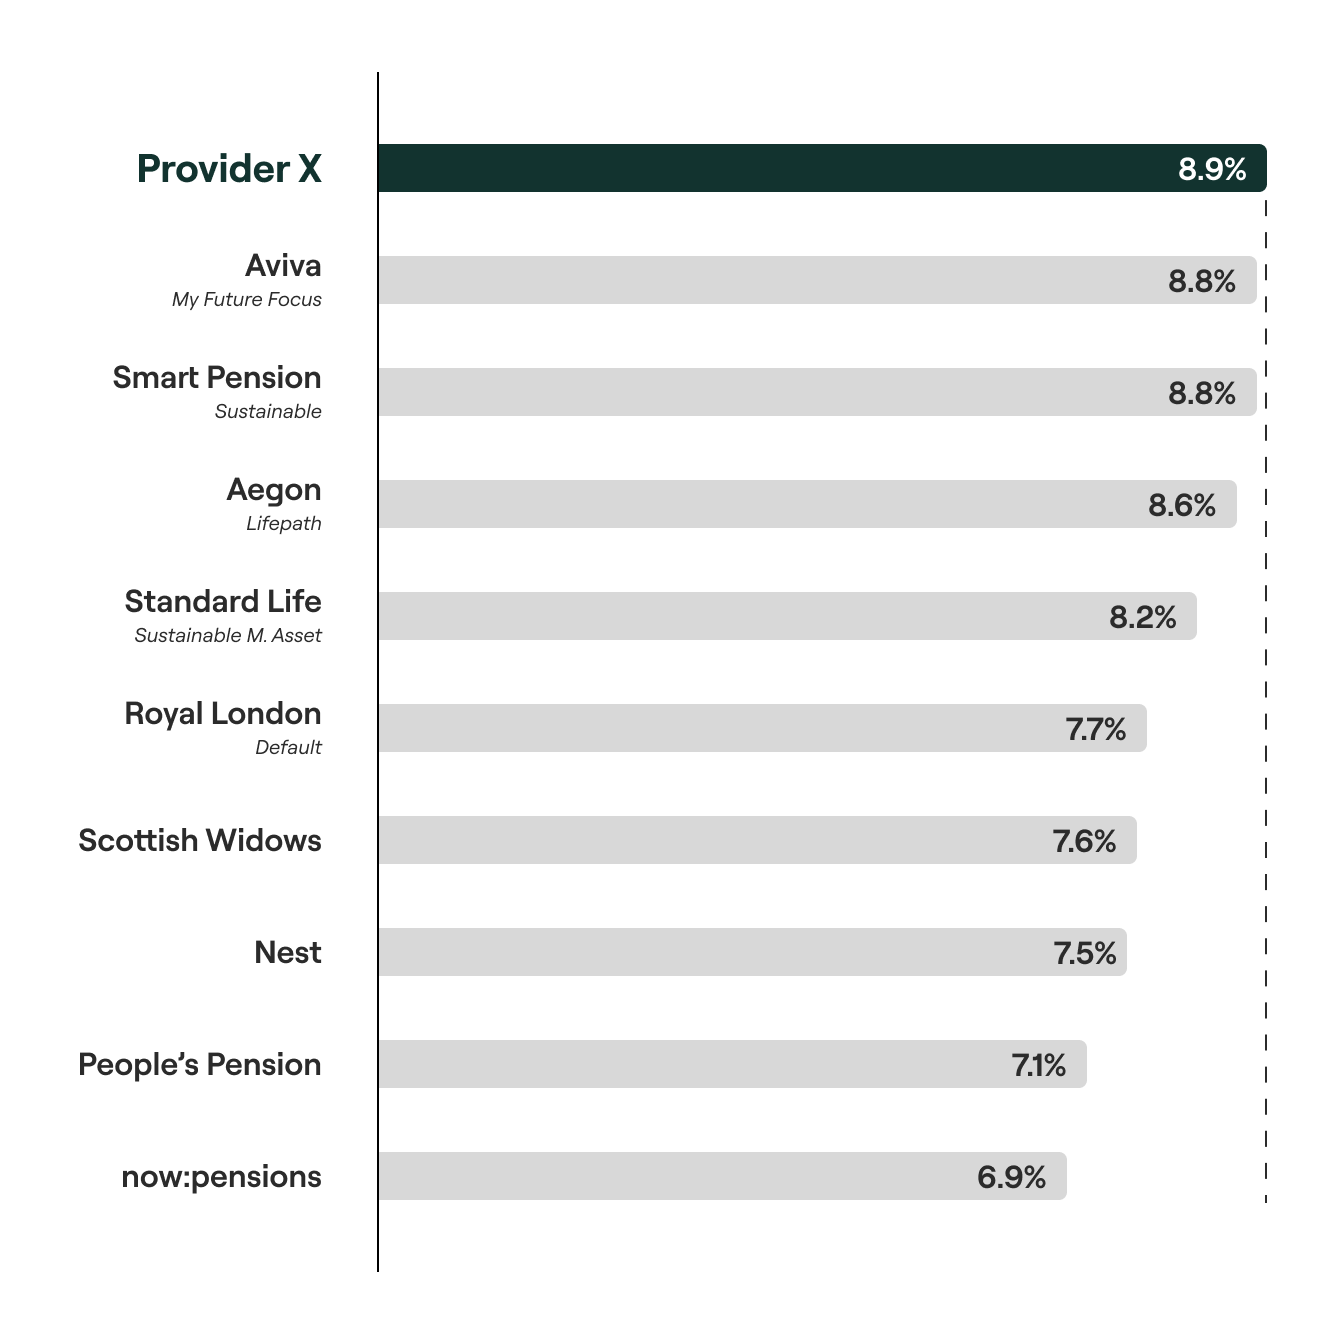
See how engagement, transfers and returns for Provider X compare with the wider market, so you can see what your team will get.
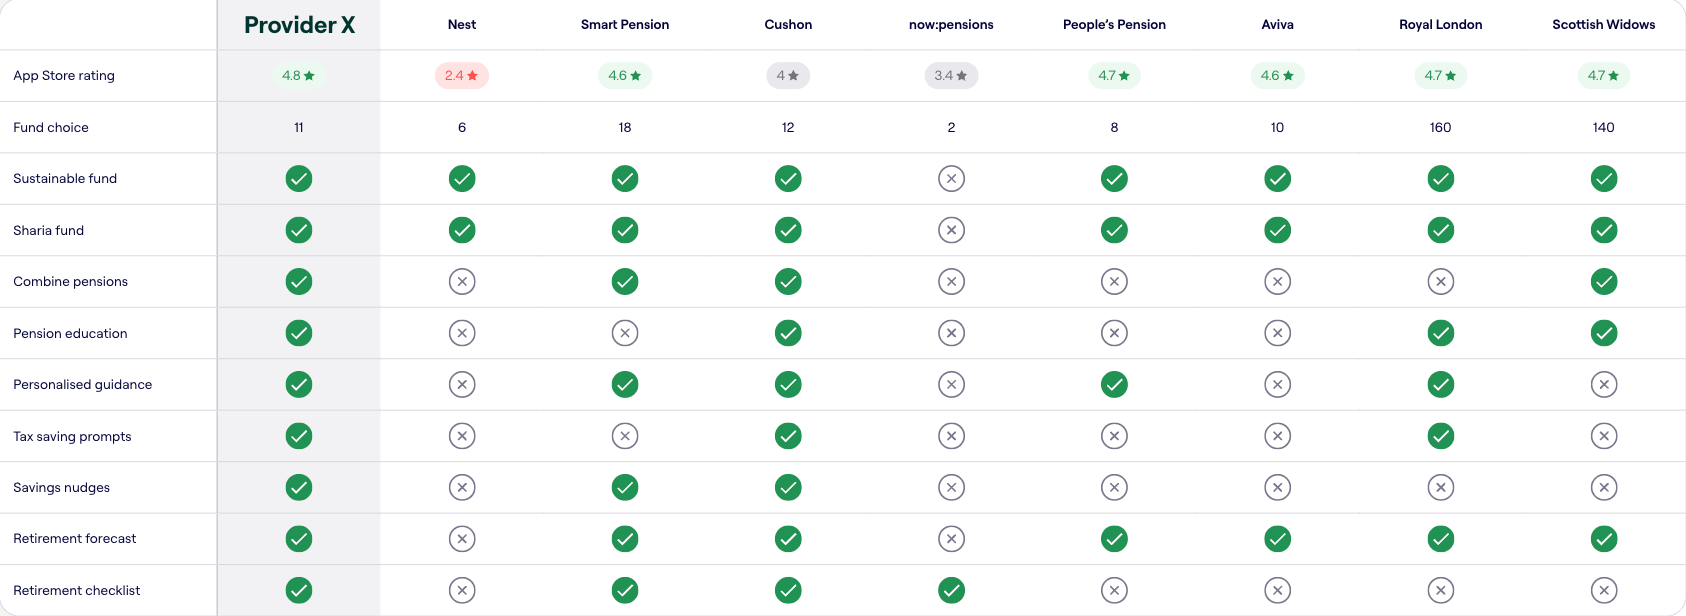
What a modern pension app looks like
Your team can check in whenever they like, in plain English. No jargon and no forms to fill in.
Pick a tab to see the kind of thing they could see.
Take a look around

See what they have saved
How much is in there, where it is invested and how it is doing. No jargon.
The value of a pension can go down as well as up.

See what retirement could look like
A projected yearly income, with different retirement ages to try. Your team can also see how changing their contributions could change the picture.
Projections are estimates, not promises.

See how your investments grow
Follow how a fund has performed, from the last six months to all time, and see what is inside it. Simple and clear.
Being on track today does not guarantee the outcome.

Know what to do next
Simple next steps, from changing contributions to bringing old pensions together. It is guidance to help your team decide, not regulated financial advice.
Which steps appear depends on each person's circumstances.
Returns that make a difference
Employees will be enrolled in our default fund, which is made up of stocks, bonds and shares. They can change their appetite for growth, but this will taper off as they get to retirement.
Provider X's returns: 8.9% a year over 3 years.
Why a small gap matters
The same pot at four different yearly returns. The 3%, 5% and 7% lines are net, which means after charges. Pick how the pot starts and how it is added to.
| Net return each year | After 10 years | After 20 years | After 30 years |
|---|
Bring old pensions together
Many people have a few pensions from past jobs, and some have lost track of one. A good pension app helps your team find them and pull them into one place.
Find them
Your team can look for old pensions from inside the app.
We sort the paperwork
Their previous providers are contacted for them, with updates in the app along the way.
Keep it when they move on
The pension can stay with them if they change jobs, so there is one less pot to lose track of.
Moving a pension is not right for everyone. Compare fees, check any valuable benefits you might give up and make sure the investments suit your goals. We cannot usually accept transfers from defined benefit pensions.